Mortgage: debt consolidation
Debt consolidation
Combining high-interest debt into a more manageable payment may help simplify your finances. We help you understand mortgage-based debt consolidation options and the costs involved.
Bring your debt together
If you are managing multiple high-interest debts, mortgage-based financing may provide an opportunity to combine them into a more manageable payment structure.
Simplify your payments
Combine multiple debts into a single financing structure where appropriate.
Reduce credit utilization
Consolidating outstanding balances may reduce your overall credit utilization.
Create a clear payoff strategy
Understand your new payment structure and create a clearer plan for managing your debt.
Explore the right financing option
Depending on your circumstances, there may be more than one way to approach debt consolidation.
Mortgage refinance
Access available home equity by refinancing your existing mortgage, where appropriate.
Second mortgage
Explore second-mortgage financing while keeping your existing first mortgage in place.
Your debt consolidation plan, step by step
Step 1
Understand your current debt
Review your existing mortgage, debts, payments, and overall financial position.
Step 2
Understand the numbers
Review available equity, potential financing, costs, and payment scenarios.
Step 3
Explore your options
Compare refinancing and second-mortgage solutions where appropriate.
Step 4
Choose your path forward
Select an approach that fits your circumstances and understand how you will manage the new payment.
It's more than just one monthly payment
Current debt
Understand the balances, interest rates, and payments you're currently managing.
Home equity
Review the available equity and potential lending options.
Costs
Consider interest, fees, penalties, and other costs associated with the financing.
Long-term plan
Make sure the strategy includes a clear plan for managing and paying down your debt.
Common questions
How does debt consolidation with a mortgage work?
Your higher-interest debts, such as credit cards or loans, are paid off using funds from a new or larger mortgage. You then make one mortgage payment instead of several.
Is it always a good idea?
Not always. A mortgage usually has a lower interest rate than a credit card, but spreading a debt over a long amortization can mean more total interest, and your home secures the new amount. Sukhpreet compares the numbers with you before you decide.
Will my credit score matter?
Yes, it is one of the things lenders look at, along with your income and your home's value. If your credit is a concern, tell us early so we can look at all the options.
What if a bank turns me down?
Other lenders have different rules, so it is worth asking. In some situations a private or alternative lender is an option, and we explain the costs and risks on our "if a bank says no" page.
Why work with Sukhpreet?
Clear options. Practical guidance. Sukhpreet helps homeowners compare financing options and understand how mortgage solutions may fit into their overall financial goals, with clear explanations, practical options, and support from start to close.
Personalized guidance
Financing options based on your goals and circumstances.
Transparent options
Understand rates, terms, features, and costs before deciding.
End-to-end support
Guidance from the initial conversation through financing and closing.
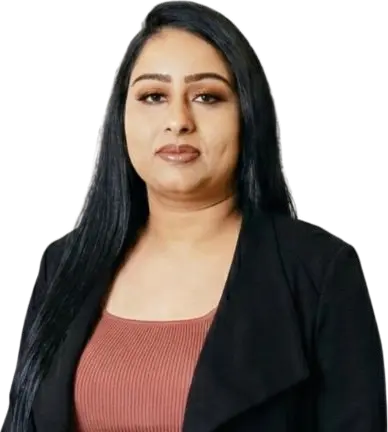
Meet Sukhpreet
Mortgage Agent, Level 1, Mortgage Alliance, Licence #10530
Sukhpreet works closely with clients to help them navigate the mortgage process with clarity and confidence.
- 20+ lender access
- Fast pre-approvals*
- Client-first guidance
*Timelines depend on document completeness and lender response.
Read Sukhpreet's full profile
Start your refinance
Share a few details and we'll call you to talk it through. The first conversation is free.
- Call
- 613-306-9900
- Office hours
- Monday to Friday9:00 AM to 6:00 PMSaturday10:00 AM to 2:00 PMSundayClosed
- Visit
- 101-14 Chamberlain Ave
Ottawa, OntarioGet directions (opens Google Maps in a new tab)